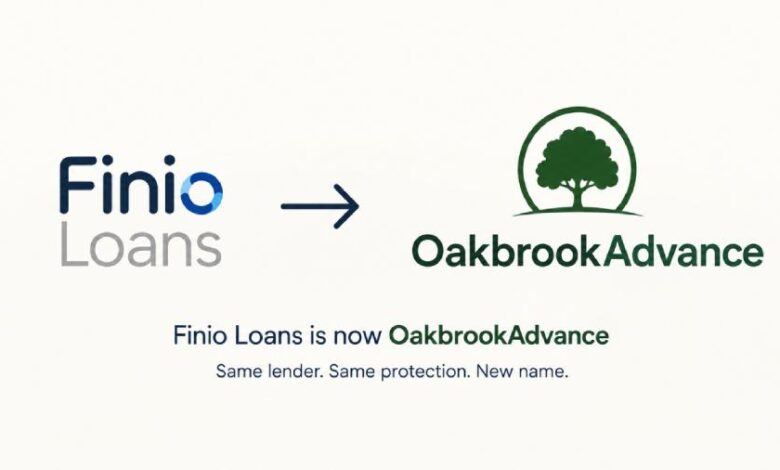
Finio Loans is a name a lot of UK borrowers still type into Google every month, and if you’ve done that recently you’ve probably landed somewhere that looks completely different to what you expected. That’s not an error, and it’s not a scam. The brand was retired in December 2025 and now trades as OakbrookAdvance. Same lender, same regulator, same legal entity behind the scenes just a different sign above the door.
The Short Answer: Finio Loans Is Now OakbrookAdvance
If you only read one section, make it this one. Finio Loans no longer exists as a customer-facing brand. In December 2025, its parent company folded the name into a single identity called OakbrookAdvance, and the old web addresses now redirect to the new site. Nothing about your credit agreement changed as part of that move the contract you signed was always with the parent company, not with the brand name printed on the marketing. Your monthly amount, your payment date and your consumer protections all carried over untouched. You don’t need to sign anything new, and you don’t need to set up a fresh direct debit.
A Quick History: Likely Loans, Finio Loans, Then OakbrookAdvance
This lender has had three names in roughly fifteen years, which explains a lot of the confusion floating around forums and comparison sites. It started life as Likely Loans back in 2011, aimed squarely at people who kept getting turned away by high-street banks. In September 2022 it rebranded to Finio Loans, keeping the same lending model but with a cleaner, more modern look. Then in December 2025 came the third change, to OakbrookAdvance. The stated reasoning was that the company wanted its customer-facing product to carry the same name as the business itself, rather than sitting behind a separate label. Whether you find that convincing or not, the practical effect for borrowers has been minimal.
Who Actually Lends the Money? Meet Oakbrook Finance Limited
Here’s the part that matters more than any brand name. Finio Loans was never a company in its own right it was a trading style of Oakbrook Finance Limited, registered in England under company number 07831517. OakbrookAdvance is a trading style of that same company. Oakbrook Finance is authorised and regulated by the Financial Conduct Authority, which is the single most important box to tick before you borrow from anyone in the UK. FCA authorisation means the lender has to follow affordability rules, treat you fairly if you fall behind, and give you access to the Financial Ombudsman Service for free if a complaint goes nowhere. You can verify all of this yourself on the FCA Register in about ninety seconds, and honestly, you should for any lender, not just this one.
What the Loans Actually Look Like
The product hasn’t been reinvented, so if you researched Finio Loans a year ago the shape of the deal will feel familiar.
Loan Amounts and Repayment Terms
You can apply to borrow between £500 and £5,000, repaid over a term of 12 to 36 months. That’s a deliberately narrow band. It’s too small for a mortgage-scale purchase and too structured for a payday-style emergency, which tells you exactly who it’s built for: someone consolidating a couple of credit cards, replacing a boiler, covering a car repair, or spreading a one-off cost over a couple of years. The exact amount and term you’re offered depends on your income, your outgoings and your credit file, so the headline range is a ceiling rather than a promise.
The Representative Example, Explained Properly
The advertised representative APR is 39.9%, with actual rates running from 20% APR up to a maximum of 69.9% APR. The official representative example works like this: borrowing £2,000 over 24 months at 39.9% APR (fixed) gives you 24 monthly repayments of £116.07 and a total amount payable of £2,785.68.
Read that last figure again, because it’s the one that matters. You receive £2,000 and hand back £2,785.68 roughly £786 in interest. The word “representative” also does a lot of quiet work here: under UK advertising rules, only 51% of approved applicants need to actually get that rate. The rest can be offered something higher, potentially much closer to that 69.9% ceiling. Always judge an offer on the personalised rate you’re shown, never the number in the advert.
How the Lender Decides Who Gets Approved
One thing that genuinely does set this lender apart from a traditional bank is how the decision gets made. Rather than relying purely on a credit score pulled from a bureau file, the application uses open banking data to look at how you handle money right now your income patterns, your regular outgoings, whether your balance survives to the end of the month. For someone whose credit file still carries a default from four years ago but who has been completely stable since, that’s a meaningfully better shot at approval than a score-only lender would give. It also means the affordability check is doing real work, which cuts both ways: it can approve people a bank wouldn’t, and it can decline people who look fine on paper but are clearly stretched.
Checking Eligibility Without Damaging Your Credit File
Before any full application, there’s a soft eligibility check. A soft search shows you whether you’re likely to be accepted and what rate you’d get, and it leaves no visible footprint on your credit file for other lenders to see. Only when you accept and move to a full application does a hard search get recorded. This is genuinely worth using, and not just here. Every hard search leaves a mark for around twelve months, and several in quick succession looks like distress borrowing to the next lender who checks. Soft-search first, every single time.
What Existing Finio Loans Customers Should Do
Almost certainly nothing. If you’re mid-way through a Finio Loans agreement, your direct debit continues on the same date for the same amount, collected by the same legal entity as before. You log in with your existing credentials on the updated portal, and the old links point you there automatically. There’s no new contract to sign and no action required on your side. The only genuine change is cosmetic different branding on the statements and emails. If something about your payments does look different, that’s worth a phone call, because it shouldn’t be.
Watch Out for Fake Finio Loans Sites and Advance-Fee Scams
Brand changes are a gift to fraudsters, because they create exactly the kind of confusion that makes a fake site plausible. The lender is explicit on this point: it will never ask for an upfront fee before paying out a loan. Anyone who calls, texts or emails claiming to be Finio Loans or OakbrookAdvance and asks for a payment to “release” or “insure” your funds is running an advance-fee scam. If it happens to you, contact your bank straight away and report it to Action Fraud. Two other habits worth building: check the web address character by character before entering anything, and look the firm up on the FCA Register rather than trusting a phone number from a search advert.
Is It Worth It? An Honest Look at the Cost
There’s no dodging it this is expensive credit, and it’s designed to be. A rate between 20% and 69.9% APR reflects a lender taking on borrowers that mainstream banks have already declined, and the price of that risk lands on the borrower. That doesn’t automatically make it a bad deal. It’s considerably cheaper than a payday loan, it’s fixed-rate so your payments never move, and it’s regulated credit that reports to the bureaus, meaning a clean repayment record genuinely rebuilds your file over two or three years.
The trap is treating a credit-building product as a reason to borrow money you don’t need. Interest at 39.9% is a real cost, not a fee for a service. If the loan is replacing more expensive debt, or covering something you’d otherwise put on a high-rate card, the maths can stack up. If it’s funding something that could wait six months, it almost never does.
Alternatives Genuinely Worth Checking First
Before signing anything at 39.9% APR, spend an hour on the alternatives. Local credit unions frequently beat this comfortably and are capped by law on what they can charge. A 0% purchase or money-transfer card can work if your file is strong enough to qualify. If the loan is for a benefits-related essential like a cooker or a bed, a Budgeting Loan or local welfare assistance may cover it interest-free. And an honest conversation with a family member, awkward as it is, costs nothing. None of these will suit everyone, but skipping the comparison entirely is how people end up paying more than they needed to.
Where to Get Free Help if Repayments Get Tight
If you’re already struggling, talk to the lender before you miss a payment rather than after. Regulated firms are obliged to work with customers in difficulty, and options like a payment holiday or a reduced arrangement exist. Alongside that, free and independent debt advice is available from StepChange on 0800 138 1111, National Debtline on 0808 808 4000, or your local Citizens Advice. These services are genuinely free anyone charging you for debt advice is selling something you can get for nothing.
Conclusion
Finio Loans has closed one chapter and opened another as OakbrookAdvance, but the substance underneath is unchanged: an FCA-regulated, near-prime lender offering £500 to £5,000 over 12 to 36 months, at rates from 20% to 69.9% APR, for people the high street tends to turn away. If you’re an existing customer, the rebrand asks nothing of you. If you’re a prospective one, the soft eligibility check is free and footprint-free, so there’s no reason not to see your personalised rate before deciding. Just go in with clear eyes about what 39.9% APR costs over two years, compare it properly against a credit union and a 0% card, and only borrow an amount you can comfortably repay if your circumstances get worse rather than better.
Also read: Andrew Salter: The Visionary Entrepreneur Behind DIRTEA and Limelyte
FAQs
Is Finio Loans still trading?
Not under that name. The brand was retired in December 2025 and now operates as OakbrookAdvance, run by the same company, Oakbrook Finance Limited.
Do I need to do anything if I have an existing Finio loan?
No. Your agreement, monthly payment and direct debit date all stay exactly as they were, and you log in to the updated portal with your existing details.
Is Finio Loans a legitimate, regulated lender?
Yes. It trades as a style of Oakbrook Finance Limited, company number 07831517, which is authorised and regulated by the Financial Conduct Authority.
How much does a Finio Loans style loan actually cost?
On the representative example, £2,000 over 24 months at 39.9% APR costs £116.07 a month and £2,785.68 in total. Rates range from 20% to 69.9% APR depending on your circumstances.
Will checking my eligibility hurt my credit score?
No. The initial eligibility check is a soft search that other lenders can’t see, and only a full application triggers a hard credit search.